

 1184 Customer Reviews
Success leaves clues, and ours are written by former customers. The TestkingPDF AICPA CPA Regulation collection has carried candidate after candidate onto the winner lists, one to two hours of daily REG practice at a time.
AICPA REG Exam Overview:
| Certification Vendor: | AICPA |
|---|---|
| Exam Name: | CPA Regulation (REG) Exam |
| Exam Number: | REG |
| Exam Format: | Task-Based Simulations (TBS), Multiple Choice Questions (MCQ) |
| Real Exam Qty: | 74 total (66 MCQs + 8 TBSs) |
| Exam Price: | USD 250–350 (varies by jurisdiction and fees) |
| Passing Score: | 75 (on a 0–99 scale) |
| Available Languages: | English |
| Related Certifications: | CPA Business Environment and Concepts (BEC legacy) CPA Information Systems and Controls (ISC) CPA Auditing and Attestation (AUD) CPA Financial Accounting and Reporting (FAR) CPA Business Analysis and Reporting (BAR) CPA Tax Compliance and Planning (TCP) |
| Exam Duration: | 240 minutes |
| Certificate Validity Period: | CPA exam credit valid for 18 months (rolling window); CPA license does not expire once issued |
| Recommended Training: | NASBA Candidate Resources AICPA CPA Exam Blueprints & Prep Resources |
| Exam Registration: | NASBA CPA Exam Services CPA Central Registration Portal |
| Sample Questions: |  |
| Exam Way: | Computer-based testing at authorized Prometric testing centers |
| Pre Condition: | No formal prerequisites for taking the CPA exam, but most jurisdictions require education (typically 120–150 semester hours) and specific accounting coursework for licensure. |
AICPA REG Exam Syllabus Topics:
| Section | Weight | Objectives |
|---|---|---|
| Topic 1: Business Law | 10–20% | - Business structure law
|
| Topic 2: Federal Taxation of Individuals | 15–25% | - Individual income taxation
|
| Topic 3: Ethics, Professional Responsibilities, and Federal Tax Procedures | 15–25% | - Ethics and professional conduct
|
| Topic 4: Federal Taxation of Property Transactions | 12–22% | - Property transactions
|
| Topic 5: Federal Taxation of Entities | 18–28% | - Business entity taxation
|
AICPA REG Exam: FAQ for Future Passers
AICPA CPA Regulation is an official AICPA certification exam, listed under the code REG. Passing it earns the Certified Public Accountant (CPA) certification at the Professional level. It also ties into CPA Auditing and Attestation (AUD), CPA Financial Accounting and Reporting (FAR), CPA Business Environment and Concepts (BEC legacy), CPA Business Analysis and Reporting (BAR), CPA Information Systems and Controls (ISC), CPA Tax Compliance and Planning (TCP). In an era of lifelong learning, this credential is one of the most efficient ways to prove your skills keep pace.
AICPA CPA Regulation gives you 74 total (66 MCQs + 8 TBSs) questions across 240 minutes. The efficient approach: one to two hours of daily timed practice in the TestkingPDF engine builds both the knowledge and the pacing, so exam day feels like simply another well-run session.
Passing AICPA CPA Regulation takes 75 (on a 0–99 scale), and the official registration fee is USD 250–350 (varies by jurisdiction and fees). Retakes cost the full USD 250–350 (varies by jurisdiction and fees) again, so treat your TestkingPDF practice scores as the decision-maker: book when the passing line sits below your everyday results, not your best ones.
The AICPA CPA Regulation syllabus is organized into 5 domains, led by Federal Taxation of Individuals (15–25%), Federal Taxation of Entities (18–28%), and Ethics, Professional Responsibilities, and Federal Tax Procedures (15–25%). The complete breakdown is above on this page; it is the fastest way to learn where your limited preparation hours belong.
No formal prerequisites for taking the CPA exam, but most jurisdictions require education (typically 120–150 semester hours) and specific accounting coursework for licensure.
Vendor policies are revised periodically, so verify the current requirements before registering.
Registration for AICPA CPA Regulation goes through the official channels below.
For planning: the exam is delivered Computer-based testing at authorized Prometric testing centers.
AICPA recommends the following training for AICPA CPA Regulation candidates.
Follow any training with daily practice on the 70 questions in the TestkingPDF REG package; sorted by authorized expert groups, they turn course theory into exam-ready skill.
Yes on both counts. Download the free demo of the AICPA CPA Regulation questions first, and browse the comments written by former customers for a second opinion. After purchase, new versions are sent to you as soon as they release, free for 365 days; after expiry, extending the update service costs 50% of the regular price.
Worry-free means a 100% money-back guarantee with stated conditions. Take the AICPA CPA Regulation exam within 60 days of purchase; if you fail, you may claim a full refund, provided the exam matches your product. Attempts within 3 days of purchase are ineligible, as are downloaded-but-unused products, free materials, and expired orders; the candidate name must match the payer name. Submit a scanned enrollment slip and the official Score Report PDF within 2 days of the exam, and claims are processed within 7 days. Alternatively, exchange for two other exam products of equal value, free, keeping the update service on your original purchase.
Delivery is instant: download your files the moment you pay, with an email copy arriving within one minute. If nothing arrives within 2 hours, check spam and contact customer service, online 24/7 with infinite patience. Installation is unlimited across your computers.
AICPA CPA Regulation Sample Questions:
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable
income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own
and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994
Form 1040.
The Moores had no capital loss carryovers from prior years. During 1994, the Moores had the following
stock transactions, which resulted in a net capital loss: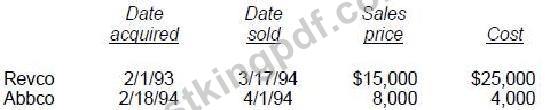
- A. $1,000
- B. $10,000
- C. $500
- D. $3,000
- E. $75,000
- F. $1,250
- G. $900
- H. $55,000
- I. $1,500
- J. $2,500
- K. $2,000
- L. $25,000
- M. $50,000
- N. $1,300
- O. $0
Correct Answer: D 🗳️
Explanation: Only visible for TestkingPDF members. You can sign-up / login (it's free).
Tom and Joan Moore, both CPAs, filed a joint 1994 federal income tax return showing $70,000 in taxable
income. During 1994, Tom's daughter Laura, age 16, resided with Tom. Laura had no income of her own
and was Tom's dependent.
Determine the amount of income or loss, if any that should be included on page one of the Moores' 1994
Form 1040.
The Moores received a stock dividend in 1994 from Ace Corp. They had the option to receive either cash
or Ace stock with a fair market value of $900 as of the date of distribution. The par value of the stock was
$ 500.
- A. $1,000
- B. $10,000
- C. $500
- D. $3,000
- E. $75,000
- F. $1,250
- G. $900
- H. $55,000
- I. $1,500
- J. $2,500
- K. $2,000
- L. $25,000
- M. $50,000
- N. $1,300
- O. $0
Correct Answer: G 🗳️
Explanation: Only visible for TestkingPDF members. You can sign-up / login (it's free).
Which of the following is subject to the Uniform Capitalization Rules of Code Sec. 263A?
- A. Editorial costs incurred by a freelance writer.
- B. Warehousing costs incurred by a manufacturing company with $12 million in annual gross receipts.
- C. Research and experimental expenditures.
- D. Mine development and exploration costs.
Correct Answer: B 🗳️
Explanation: Only visible for TestkingPDF members. You can sign-up / login (it's free).
Which payment(s) is(are) included in a recipient's gross income?
I. Payment to a graduate assistant for a part-time teaching assignment at a university. Teaching is not a
requirement toward obtaining the degree.
II. A grant to a Ph.D. candidate for his participation in a university-sponsored research project for the
benefit of the university.
- A. Both I and II.
- B. Neither I nor II.
- C. II only.
- D. I only.
Correct Answer: A 🗳️
Explanation: Only visible for TestkingPDF members. You can sign-up / login (it's free).
The uniform capitalization method must be used by:
I. Manufacturers of tangible personal property.
II. Retailers of personal property with $2 million dollars in average annual gross receipts for the 3
preceding years.
- A. Both I and II.
- B. Neither I nor II.
- C. II only.
- D. I only.
Correct Answer: D 🗳️
Explanation: Only visible for TestkingPDF members. You can sign-up / login (it's free).




Emmanuel -
The service is pretty good, and they gave me lots of advice in the process of selecting REG exam materials.